
Fall Home Maintenance Must-Dos
October 19, 2026
A competitive retirement plan can be a powerful tool for attracting and retaining skilled employees. While most business leaders recognize the value of offering a 401(k), not everyone understands how much administrative and financial responsibility comes with managing one.
For print and graphic communications businesses that are FGA, PINE and PGCA members, there’s another option worth considering: a Multiple Employer Plan (MEP). Through the GKG-sponsored Print and Graphics Retirement Plan, eligible employers can simplify administration, reduce certain fiduciary responsibilities, and potentially lower costs while maintaining a competitive retirement benefit.
The Hidden Responsibilities of a Traditional 401(k)
When a business sponsors its own single-employer 401(k), it assumes a range of administrative and fiduciary responsibilities. Even with outside service providers, employers remain responsible for overseeing their plan and fulfilling their obligations.
These responsibilities can include plan administration, investment oversight, regulatory compliance, annual reporting, and employee support, and typically falls on business owners, finance leaders, or HR professionals who are already balancing the demands of running daily operations.
While outsourcing certain tasks can help, delegating administration doesn’t automatically eliminate fiduciary responsibility.
Share the Administrative & Financial Load (With Us)
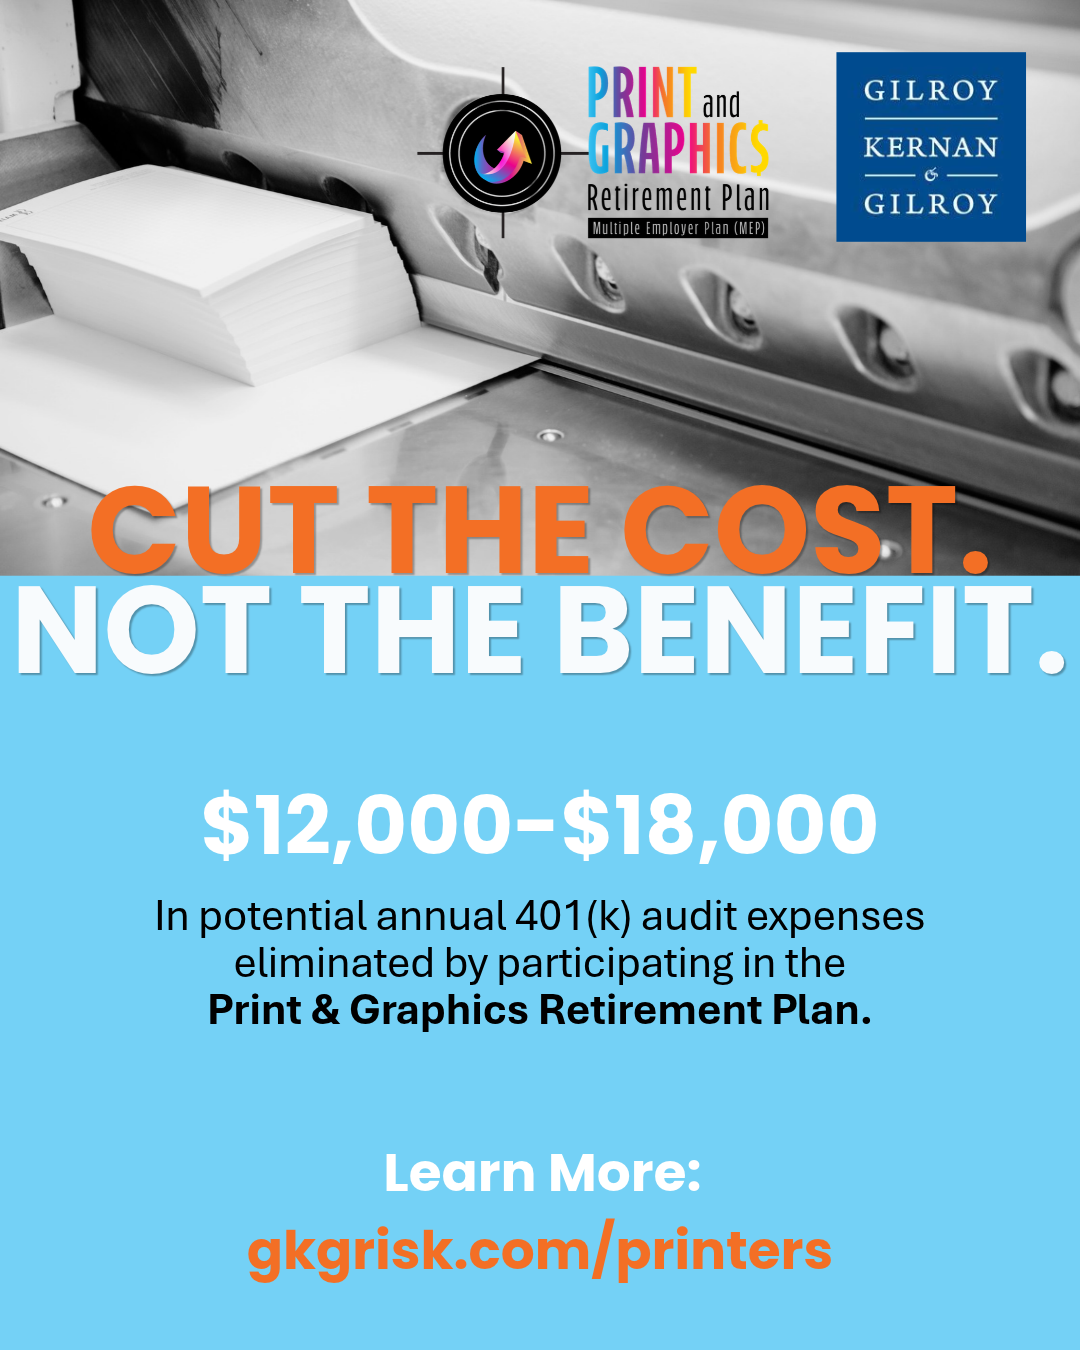
An MEP allows eligible businesses with a common connection, such as membership through a professional association like PINE, to participate in a single retirement plan with centralized administration and professional oversight, rather than each business maintaining its own independent plan.
Through The Print and Graphics Retirement Plan, participating employers can streamline responsibilities such as employee eligibility tracking, required communications, compliance testing, investment selection and monitoring, and annual reporting.
One of the best advantages? No separate annual plan audit or Form 5500 filing. For businesses required to undergo an annual 401(k) audit, that process can typically cost $12,000-$18,000 each year. Under the MEP structure, the plan absorbs that annual cost, eliminating that expense for participating employers.
Joining an MEP doesn’t mean giving up control. Employers maintain flexibility in areas such as eligibility requirements, matching contribution formulas, and certain plan features, while benefiting from shared resources and specialized expertise. Employers also retain important obligations, including selecting and monitoring the MEP provider, coordinating payroll contributions, and supplying necessary employee information.
The goal isn’t to eliminate accountability; It’s to put specialized responsibilities in the hands of qualified professionals so you can focus more on running your business.
Are you working harder than your 401(k)?
Administrative efficiency is only one part of the equation. A retirement plan should also be evaluated for its overall cost, investment options, employee experience, and alignment with business goals.
For some employers, an MEP may offer cost efficiencies through pooled resources or elimination of audit expenses. For others, the greatest value may be access to retirement plan specialists and reduced administrative demands.
Ultimately, the right approach depends on your organization’s needs, existing plan structure, and long-term objectives.
Ready to take a closer look at your retirement plan?
Whether you currently sponsor a 401(k), are considering offering one for the first time, or haven’t reviewed your plan recently, GKG can help you evaluate your current plan structure, responsibilities, and costs, to determine whether the Print and Graphics Retirement Plan could be the right fit for your organization.
To learn how GKG helps print employers evaluate retirement plan strategy, click here or contact Sarah Armstrong, Andy Biernat, Ross Kraft.
Sarah Armstrong
SarahA@gkgrisk.com
315-838-8083
Andrew Biernat
AndrewB@gkgrisk.com
315-794-6475
Ross Kraft
RossK@gkgrisk.com
315-794-6522